MOVA / Buy-to-Let Mortgages

Buy-to-let mortgage advice

Mortgage advice for personal ownership, limited companies and portfolios. Start with the property, rent and borrowing you have in mind.

30-minute initial phone call · No cost · No pressure to proceed

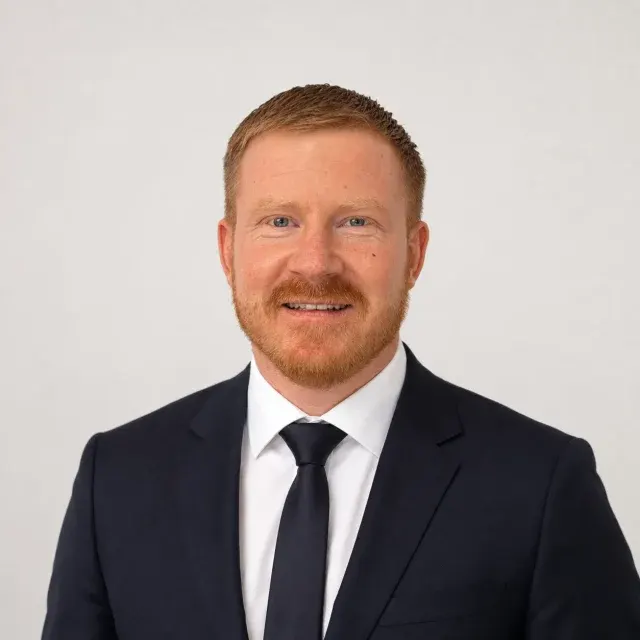
Steven Cooper, MOVA founder and mortgage adviser
Steven Cooper
Founder · MOVA Mortgages
  • Review the property and rent
  • Check the ownership and borrowing
  • Prepare the lender evidence
The MOVA panel

Buy-to-let lenders on our panel

  • The Mortgage Works
  • BM Solutions
  • Paragon
  • Accord Mortgages
  • Coventry
  • Leeds Building Society
  • Virgin Money
  • NatWest
  • Barclays
  • Santander
  • HSBC
  • TSB
  • Aldermore Mortgages
  • Kensington
  • Kent Reliance
  • Landbay
  • Keystone
  • Fleet Mortgages
  • Foundation Homeloans
  • The Mortgage Lender
  • Vida Home Loans
  • CHL Mortgages
  • Lendco
  • LendInvest
  • Molo
  • Moda Mortgages
  • MT Finance
  • Quantum Mortgages
  • Zephyr Homeloans
  • West One
  • United Trust Bank
  • Hampshire Trust Bank
  • Together
  • Precise Mortgages
  • Gatehouse Bank

Finance for landlords

The right starting point for your property plans.

MOVA reviews the property, rental income, borrowing and ownership structure before exploring lender options.

01

Personal ownership

For a first rental purchase, a further property or refinancing in your own name. We review rental cover, deposit or equity and your wider commitments.
02

Limited-company buy-to-let

For borrowing through a company. We look at the company structure, directors, property and lender requirements, including any personal guarantee.

03

Portfolio landlords

For several rental properties or a wider refinancing plan. Bring an overview of property values, rents and outstanding mortgages.

An HMO, multi-unit building or mixed-use property needs an early discussion about the property and finance route.

Explore property finance →

Ownership decisions can affect tax and legal obligations. Your accountant and solicitor should advise on the structure; MOVA reviews the finance.

Start with the investment, not a headline loan size.

Share the price or value, expected rent, available deposit and the type of property. Rental coverage calculations vary between lenders. A property that works on a simple monthly calculation may still fall outside a lender’s criteria. Consider void periods, maintenance and other ownership costs in your own plan.

Existing landlords: bring the whole picture.

If you already own rental properties, information about the portfolio may matter as well as the new property. Keep a schedule of values, mortgages, rents and ownership structures. Discuss refinancing and product end dates together where that helps avoid looking at one commitment in isolation.

  • HMOs, multi-unit buildings and unusual tenancies can require a more specialist assessment.
  • Mixed residential and commercial property should be discussed separately.

Ownership is more than a mortgage decision.

Buying personally or through a limited company can have different consequences. MOVA can discuss mortgage options, but legal and tax advice should come from an appropriately qualified professional. Do not choose a structure on the basis of an advertised mortgage rate alone.

Your questions, answered

Your questions, answered

Have a question that is specific to you?

Can a first-time landlord enquire?

Yes. Explain your plans and experience so Steven can establish which options may be relevant. Availability remains subject to lender criteria.

Is interest-only the same as paying off the mortgage?

No. Interest-only payments do not reduce the capital balance. You need an acceptable plan to repay the loan.

Are buy-to-let mortgages regulated?

Some forms of buy-to-let mortgage are not regulated by the Financial Conduct Authority. The position depends on the arrangement and circumstances.

A practical next step

Discuss your buy-to-let plans.

Tell Steven about the property, expected rental income and your plans as a landlord. Get separate tax or legal advice where your ownership decisions need it.

Your home may be repossessed if you do not keep up repayments on your mortgage. There may be a fee for mortgage advice. The amount will depend on your circumstances and will be explained and agreed before you choose to proceed. Some forms of buy-to-let mortgage are not regulated by the Financial Conduct Authority.