MOVA / Critical illness cover

Financial breathing room after a covered diagnosis.

A lump sum could help with your mortgage, household costs or time away from work. We’ll explain what the policy covers, how a claim qualifies and how it fits your budget.

Personal advice · No pressure to proceed
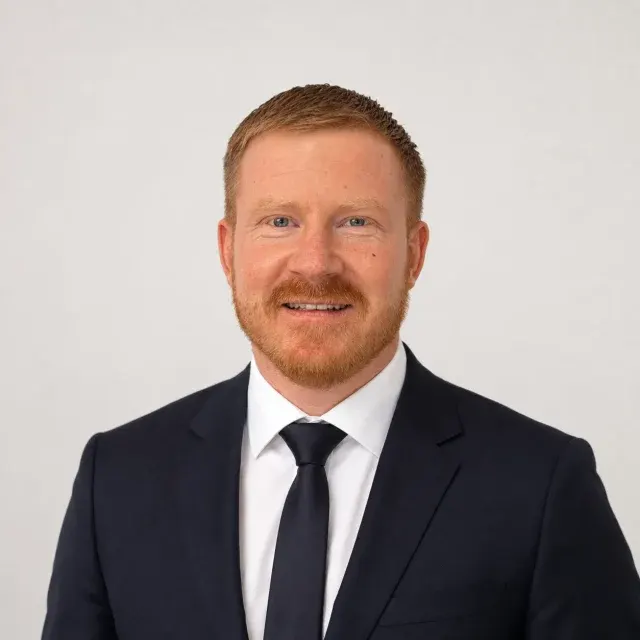
Steven Cooper
Steven Cooper · FounderClear explanations. A personal conversation.

A claim must meet the policy’s condition and severity definitions, exclusions and any survival period. Critical illness cover does not cover every illness.
Illustrative couple walking together outdoors
The MOVA panel

Critical illness cover providers

  • Legal & General
  • Royal London
  • Aviva
  • Zurich
  • LV=
  • Vitality
  • Guardian
  • Scottish Widows
  • Beagle Street

Understand the options

Look beyond the number of conditions.

The differences that matter are in the wording and how the policy supports your household.

01

What qualifies for payment

A diagnosis must meet the insurer’s definition, including any required severity or treatment criteria.

What MOVA explainsThe conditions, definitions, exclusions and any survival period that apply to the recommended policy.

02

How much could be paid

The main benefit is usually a lump sum. Some policies also have additional or partial payments for specified conditions.

What MOVA explainsWhich benefits are included, the amount each can pay and whether a payment reduces other cover.

03

What remains after a claim

Standalone and combined life-and-critical-illness policies can work differently after a payout.

What MOVA explainsWhether cover ends, reduces or continues, and what would remain for you or your family.

A longer list of illnesses does not automatically mean better cover for you. Definitions, exclusions, benefit structure and affordability all matter.

Make it personal

Decide what the money would need to do.

Start with the financial pressure a serious illness could create, then assess the cover alongside your existing benefits.

  • Keep the household running

    Mortgage or rent, bills and family support may continue while your circumstances change.

  • Allow room for recovery

    Think about income changes, additional help and practical costs. A payout can be used according to your needs.

  • Fit with your other policies

    Life cover and income protection do different jobs. We will consider existing protection and workplace benefits before recommending changes.

What MOVA does for you

Advice you can follow. Support at each step.

  1. 01

    Understand the need

    We look at your commitments, existing policies, workplace benefits and a budget you can maintain.

  2. 02

    Compare and explain

    We compare suitable options from our panel and explain the recommendation, costs, limits and exclusions.

  3. 03

    Help put cover in place

    We support the application, explain the insurer’s final terms and confirm the agreed start date. An enquiry does not put cover in force.

Already have cover?

Review it before replacing it.

Bring your current policy and workplace benefits. We will look at the cover you have and how it fits your life today. Keeping an existing policy may be the right outcome.

Discuss my existing cover

Do not cancel existing cover until any replacement has been accepted and is in force. New premiums, exclusions and terms may differ.

Your questions, answered

Critical illness cover questions.

Does it cover every cancer or serious illness?

No. The diagnosis must satisfy the particular policy definition and severity requirements. Exclusions and any survival period also apply.

Is critical illness cover the same as income protection?

No. Critical illness cover usually pays a lump sum for a specified condition. Income protection pays a regular benefit for qualifying inability to work after the waiting period.

Can children’s cover be included?

Some policies include or offer children’s cover, with their own conditions, age limits and payment limits. We can explain what is available and whether it is included or costs extra.

Will my medical history affect the application?

It can affect availability, premiums and exclusions. Answer the insurer’s questions accurately. Medical information should be provided through the appropriate advice and application process, not the website enquiry.

Should I replace existing cover?

A review should compare your current terms with any proposed policy. Older policies may contain valuable features. Do not cancel existing cover until a replacement has been accepted and is in force.

Your next step

Understand the cover before you choose.

Talk through what you would want a payment to support. Steven will explain suitable options and the details that make a difference.

Prefer to call? 0330 633 0379

Cover is subject to eligibility, underwriting, policy terms, definitions and exclusions. Premiums and any relevant fees or charges will be explained before you proceed. Do not cancel existing cover until a replacement has been accepted and is in force.