MOVA / Home insurance

Cover for your home and what’s inside.

Buying, moving or reviewing a renewal? We’ll help you compare buildings and contents cover, understand the limits and get the start date right.

Personal advice · No pressure to proceed
Steven Cooper
Steven Cooper · FounderClear explanations. A personal conversation.

Cover depends on the insured events, limits, excesses and exclusions in the policy. Check when you become responsible for insuring the property.
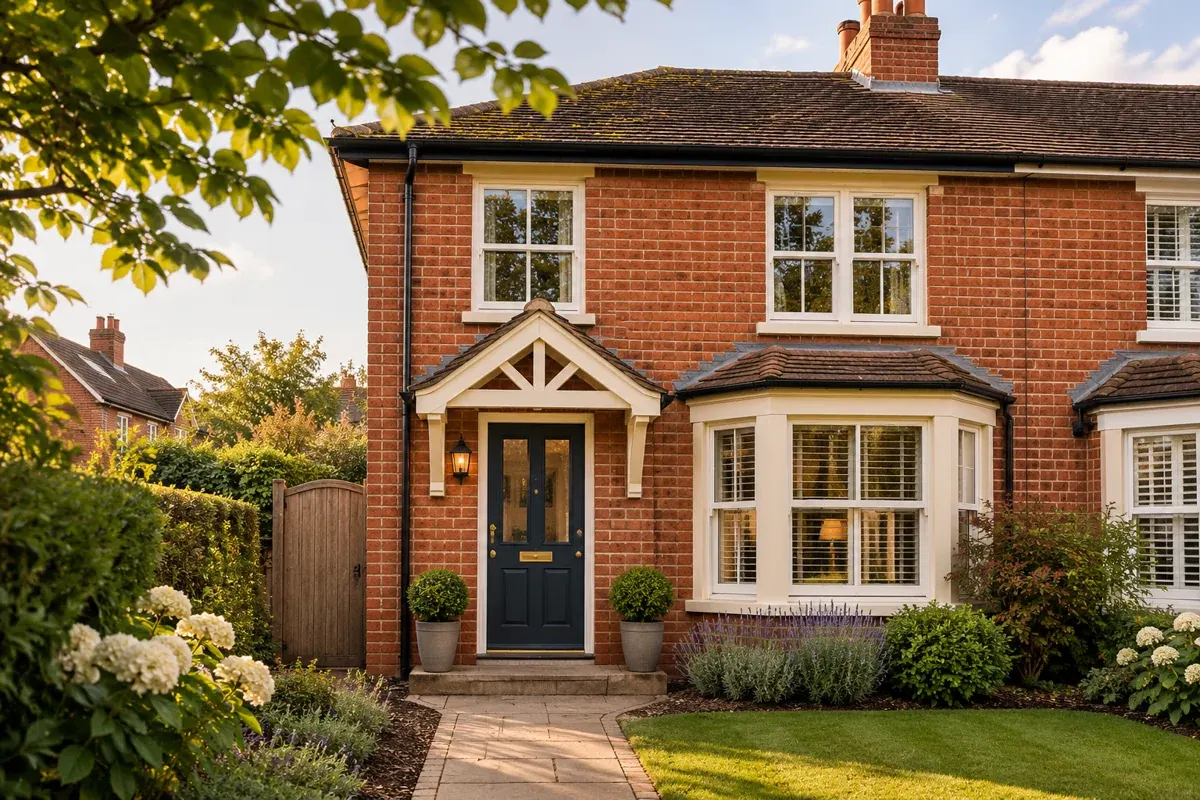
Welcoming brick home with a garden
The MOVA panel

Home insurance providers

  • Allianz
  • Assurant
  • Brown & Brown
  • Ceta
  • everywhen
  • First2Protect
  • HIVE
  • LV=
  • MMS
  • Paymentshield
  • Source
  • Uinsure

Understand the options

The building. Your belongings. The extra detail.

Choose the cover around the property and how you use it, with a clear understanding of what is included.

01

Buildings insurance

Covers the structure and permanent fittings against insured events, subject to the policy terms.

What to checkThe rebuilding basis, excesses and exclusions. A property’s market value is not the same as its rebuilding cost.

02

Contents insurance

Covers belongings in the home against insured events, within the policy’s limits.

What to checkThe overall sum insured, single-item limits and whether valuable items need to be specified.

03

Optional extras

Accidental damage, belongings away from home and other options may be available.

What to checkWhat is already included, additional premiums and any separate limits or exclusions. Extras vary between policies.

Buildings and contents are different covers. A mortgage lender’s buildings requirement does not mean your belongings are insured automatically.

Make it personal

Get the timing and property details right.

A move or renewal is a useful time to check how the cover fits the way the home is owned and used.

  • Buying a property

    Your conveyancer should confirm when you become responsible for insurance under the contract. Do not assume it starts only when you collect the keys.

  • Owning a leasehold home

    Check the freeholder’s or management company’s buildings policy and your responsibilities. You may still need your own contents cover.

  • Changing how the home is used

    Tell the insurer about relevant changes such as works, letting, business use or long unoccupied periods. These can affect cover.

What MOVA does for you

Advice you can follow. Support at each step.

  1. 01

    Understand the need

    We discuss the property, how it is used, the cover already in place and when the new policy should start.

  2. 02

    Compare and explain

    We compare suitable options from our panel and explain the recommendation, costs, limits and exclusions.

  3. 03

    Help put cover in place

    We support the application, explain the insurer’s final terms and confirm the agreed start date. An enquiry does not put cover in force.

Already have cover?

Review it before replacing it.

Bring your current policy and renewal details. We will look at what is covered, the excesses, the premium and any changes to your property.

Discuss my existing cover

Coordinate any change so the new cover starts when needed and avoid an unintended gap in cover.

Your questions, answered

Home insurance questions.

Will my lender arrange insurance for me?

Do not assume so. Lenders normally require suitable buildings insurance, but you should check your mortgage conditions and make the necessary arrangements.

When should buildings cover start for a purchase?

Ask your conveyancer when responsibility passes to you under the contract. The correct date can be earlier than completion or collecting the keys.

Does buildings cover include contents?

Not automatically. Buildings and contents insure different things. Check whether the policy includes both and whether the limits are suitable.

Can I review my renewal with MOVA?

Yes. Bring the renewal, current policy schedule and details of any changes. We can help you compare the cover, excesses and cost, rather than looking only at the premium.

Do I need cover if the freeholder insures the building?

Check the lease and the buildings policy first. It may not insure your belongings or all of your responsibilities. Avoid assuming the block policy covers everything.

Your next step

Move or renew with the details clear.

Tell Steven about the property and when you need cover. We’ll help you understand the suitable options and next steps.

Prefer to call? 0330 633 0379

Cover is subject to the insurer’s acceptance, policy terms, limits, excesses and exclusions. Premiums and any relevant fees or charges will be explained before you proceed.