MOVA / Income protection

Protect the income your life runs on.

If illness or injury stops you working, income protection can replace part of your earnings. We’ll help you assess your sick pay, savings and essential costs before comparing cover.

Personal advice · No pressure to proceed
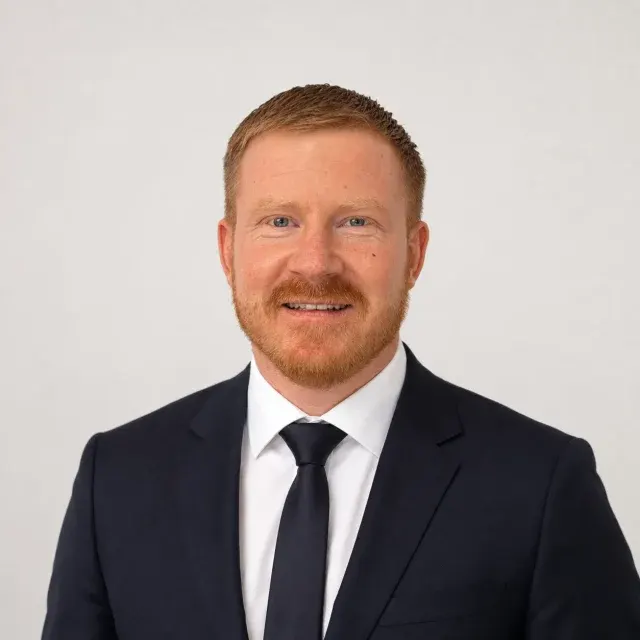
Steven Cooper
Steven Cooper · FounderClear explanations. A personal conversation.

Benefits depend on the policy’s incapacity definition, waiting period, income limits and claim terms. Income protection does not normally cover redundancy.
Illustrative designer reviewing materials at work
The MOVA panel

Income protection providers

  • Legal & General
  • Royal London
  • Aviva
  • Zurich
  • LV=
  • Vitality
  • The Exeter
  • Guardian
  • British Friendly
  • Cirencester Friendly
  • Holloway Friendly
  • National Friendly
  • Shepherds Friendly

Understand the options

Three decisions shape your cover.

A useful policy needs to fit both your working life and the support you already have.

01

When payments start

The deferred period is the waiting time before a qualifying claim begins to pay.

Start withYour employer’s sick pay or other continuing income, when it reduces and the savings you could use.

02

How long a claim can pay

The benefit period is different from the policy term. Some policies limit each claim to a set period; others may pay for longer.

Start withThe commitments you need to maintain and the trade-off between the premium and potential claim duration.

03

What unable to work means

Own occupation, suited occupation and other definitions can lead to different claim outcomes.

Start withYour job duties, employment status and the precise definition in the policy. Cover is subject to underwriting.

The insured benefit is usually a proportion of eligible earnings, not your whole salary. The insurer’s income rules and other benefits can affect what is payable.

Make it personal

Employed or self-employed: start with the income that would continue.

The right waiting period depends on what happens to your finances when you stop working.

  • If you are employed

    Check the actual sick-pay policy, how long full and reduced pay last, and any group income protection through work.

  • If you are self-employed

    Consider the earnings that would stop, income that could continue and how your income is evidenced. Personal cover does not automatically insure every business cost.

  • If your work changes

    A new role, income change or different employer benefits can be a useful prompt to review existing cover.

What MOVA does for you

Advice you can follow. Support at each step.

  1. 01

    Understand the need

    We look at your commitments, existing policies, workplace benefits and a budget you can maintain.

  2. 02

    Compare and explain

    We compare suitable options from our panel and explain the recommendation, costs, limits and exclusions.

  3. 03

    Help put cover in place

    We support the application, explain the insurer’s final terms and confirm the agreed start date. An enquiry does not put cover in force.

Your household buffer

How long could your savings help?

Use the household budget tool to explore what might happen to your regular costs if your income stopped.

Explore the household buffer

This is a simple budget illustration, not an insurance quote or an assessment of the benefit you can claim.

Your questions, answered

Income protection questions.

Will it replace all my take-home pay?

Usually not. Insurers apply benefit limits and their own earnings calculations. Other continuing income or benefits may affect the amount payable.

Does it pay as soon as I become ill?

Normally there is a deferred period before qualifying payments start. The policy’s incapacity definition and other claim conditions must also be met.

Can I get cover if I am self-employed?

You can discuss cover as a self-employed person. Available benefits and terms depend on your occupation, earnings evidence, underwriting and the insurer’s criteria.

Does it cover losing my job?

Income protection is designed for qualifying illness or injury. It does not normally cover redundancy or a lack of work.

Will my premium stay the same?

This depends on the structure. Premiums can be fixed, reviewable or increase with age or selected cover increases. We will explain how the recommended policy’s premiums can change.

Your next step

Make a plan for the income you depend on.

Bring your sick-pay details, regular costs and existing cover. Steven will help you understand suitable options and the waiting period to consider.

Prefer to call? 0330 633 0379

Cover is subject to eligibility, underwriting, policy terms, definitions and exclusions. Premiums and any relevant fees or charges will be explained before you proceed. Do not cancel existing cover until a replacement has been accepted and is in force.