MOVA / Complex Credit Mortgages

Mortgage advice with a complex credit history

A missed payment, default, CCJ or previous decline needs context. Talk through the details with Steven before considering your next application.

30-minute initial phone call · No cost · No pressure to proceed

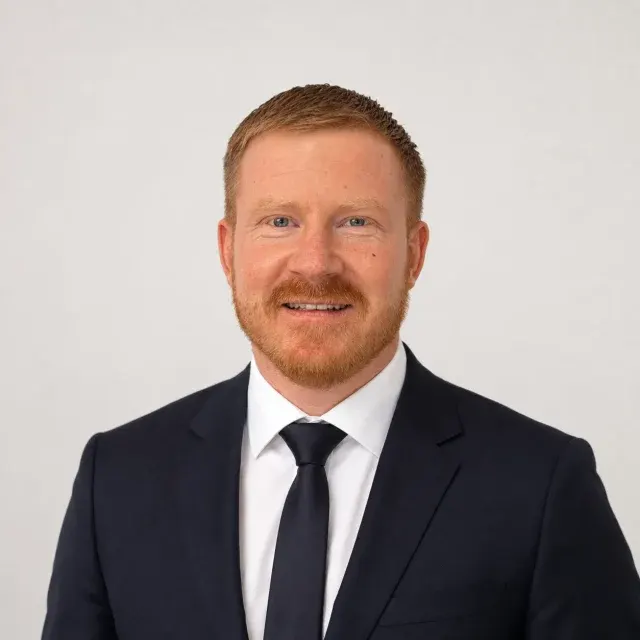
Steven Cooper, MOVA founder and mortgage adviser
Steven Cooper
Founder · MOVA Mortgages
  • Build a clear credit timeline
  • Review your current position
  • Explain a realistic next step
The MOVA panel

Specialist mortgage lenders

  • Kensington
  • Pepper Money
  • Bluestone Mortgages
  • Aldermore Mortgages
  • The Mortgage Lender
  • Vida Home Loans
  • United Trust Bank
  • West One
  • Together
  • Foundation Homeloans
  • Precise Mortgages
  • Harpenden Building Society
  • Mansfield Building Society
  • Market Harborough
  • Family Building Society

Start with the facts

What happened, when, and where things stand now.

A credit issue does not tell the whole story. MOVA reviews the details before deciding whether a lender enquiry or a later review is the sensible next step.

01

Missed payments or defaults

Discuss the type of account, dates, amounts and whether the balance is now settled.
02

CCJs or past arrangements

Explain the dates and current status of any county court judgments, debt-management arrangement or insolvency.

03

A previous mortgage decline

Review the reason given, what has changed and the evidence needed before considering another application.

Your first conversation establishes: the credit timeline, deposit or equity, affordability and the next information to review. It does not run a mortgage application or promise acceptance.

Talk it through →

Please do not upload a credit report in the website enquiry. Steven will explain how to provide relevant documents securely if needed.

Start with an accurate picture.

A credit score is only part of the information a lender considers. It helps to know what your credit reports actually show, including dates, balances and whether an issue has been resolved. If information is wrong, use the relevant credit reference agency’s process to question it.

A previous decline is useful information.

Tell Steven which type of application was declined and what explanation you received. Historic defaults, missed payments, CCJs and arrangements are not identical situations. A conversation can help establish what needs closer review before considering another application. No outcome can be guaranteed.

Sometimes preparation comes before an application.

The useful next step may be gathering evidence, checking an error or allowing time for circumstances to settle. If essential bills or current mortgage payments are becoming difficult, contact your lender and seek free debt advice. Taking on new borrowing is not a substitute for dealing with financial difficulty.

Your questions, answered

Your questions, answered

Have a question that is specific to you?

Does an enquiry leave a credit search?

This website enquiry is not a mortgage application or credit check. Any later lender search should be explained as part of the application process.

Can you guarantee a lender will accept me?

No. Lending depends on the full circumstances, the property and lender criteria.

Should I send my credit report through this form?

No. Explain the general issue without uploading financial documents. Steven will explain an appropriate next step for reviewing detailed information.

A practical next step

Explain your circumstances to Steven.

Bring the dates and details of any credit issues, alongside an outline of your income and deposit. Steven can help you understand the questions to resolve before an application.

Your home may be repossessed if you do not keep up repayments on your mortgage. There may be a fee for mortgage advice. The amount will depend on your circumstances and will be explained and agreed before you choose to proceed.